

Compared across carriers.Explained with the math.
An independent insurance agency licensed in Arizona, Nevada, Utah and Idaho. We compare your current policy against the carriers we represent, show the numbers, and say when keeping what you have is the right call. The analysis costs nothing.
- Independent
- No fee for the analysis
- Licensed in Arizona, Nevada, Utah, Idaho
- Mutual of Omaha
- UnitedHealthcare
- Aetna
- Humana
- Cigna
Coverage
One review, the whole market.
Every line we write, in four groups. The analysis compares what you have against the carriers we represent, line by line.
Auto & Home
- Auto Insurance
- Home Insurance
- Renters Insurance
- Umbrella Insurance
- Motorcycle Insurance
- Landlord / Rental Property Insurance
Life
- Life Insurance
- Term Life Insurance
- Whole Life Insurance
- Indexed Universal Life (IUL) Insurance
- Annuities
Health & Medicare
All personal linesCommercial
- General Liability Insurance
- Business Owners Policy (BOP)
- Commercial Auto Insurance
- Workers' Compensation Insurance
- Professional Liability (E&O) Insurance
- Cyber Liability Insurance
When to review
Coverage should keep up with your life.
A policy review checks that what you carry still matches what you own and owe. We recommend one at each of these moments; it takes twenty minutes and costs nothing.
Request a quoteA new home
Dwelling limits, replacement cost and the umbrella above them are set once and rarely revisited.
A new child
Life coverage is sized to what you would leave behind; a dependant changes that number.
A new job
Employer benefits change what you carry yourself: disability, life and health all move.
Approaching retirement
Medicare enrollment windows, annuity income and the policies you no longer need.
Recognition
Circle of Champions, plan year 2025.
Awarded to Daniel Ellis, principal advisor, by UnitedHealthcare for excellence in serving Medicare clients, plan year 2025. It is a personal recognition of a named producer for one plan year, and it is dated.
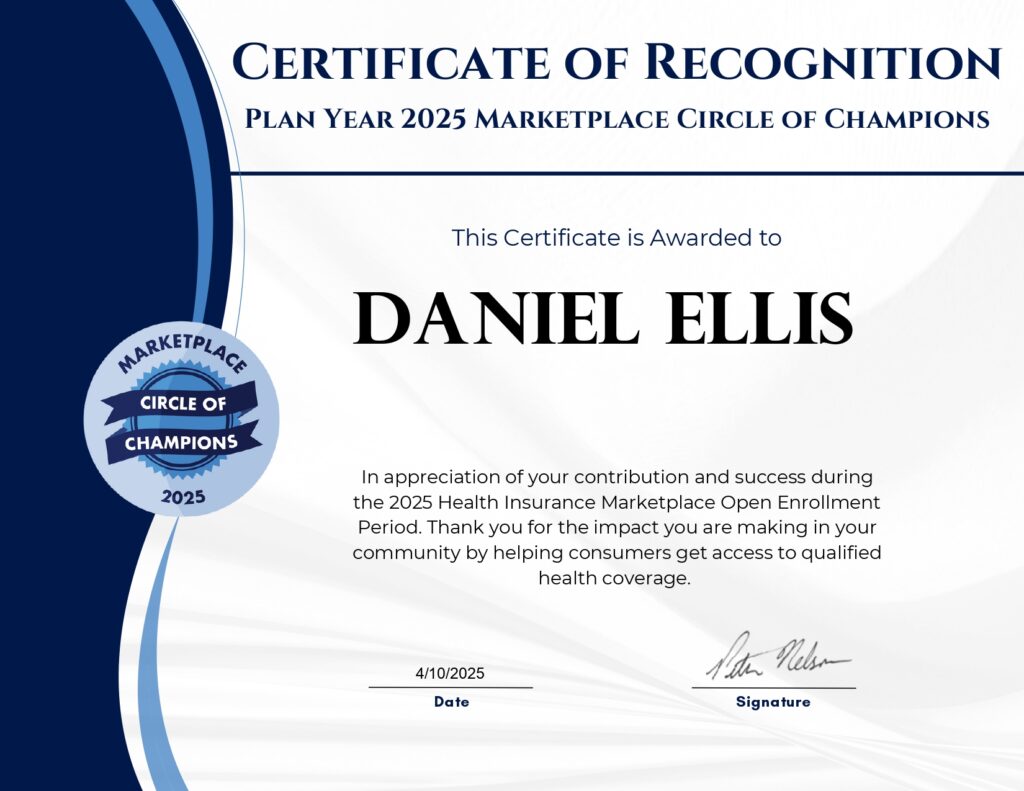
The certificate, plan year 2025 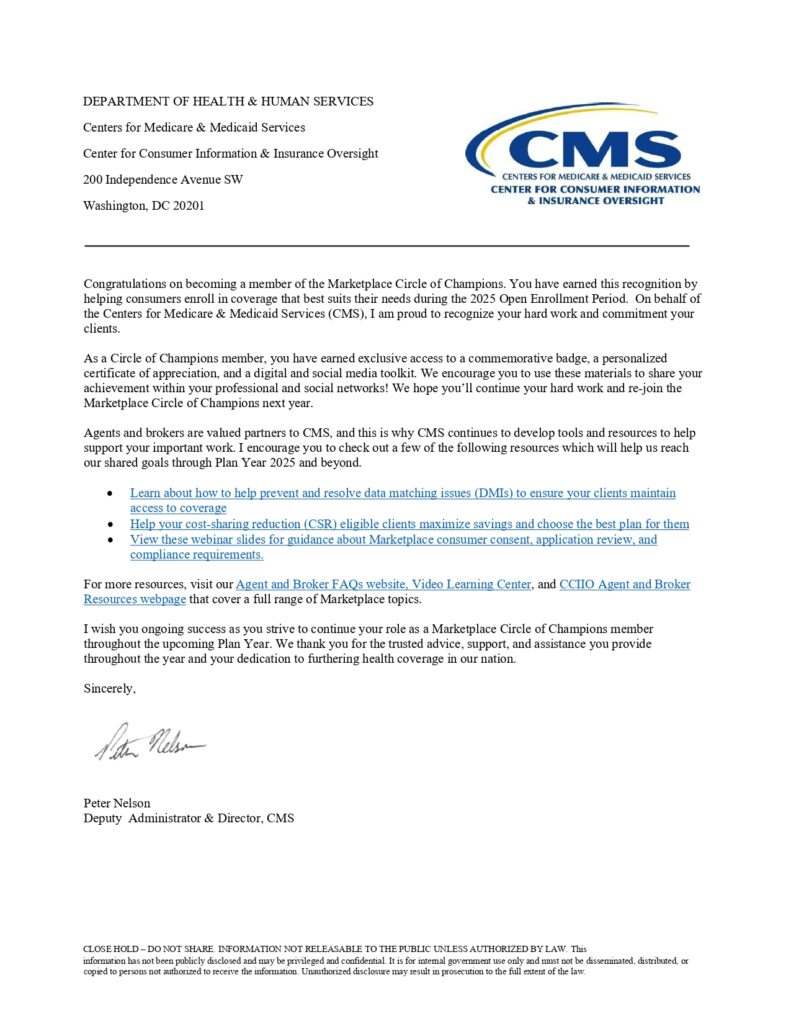
The appreciation letter, plan year 2025


Questions
Asked and answered.
How much liability coverage should I carry?
Enough that a bad crash does not reach your savings, your home equity or your future wages. The state minimum protects the other driver, not you. A common starting point for a household with assets is a limit well above the minimum with an umbrella policy on top; the analysis puts a number on it from what you own and earn.
How much dwelling coverage do I need?
Enough to rebuild the house at today's construction cost, not what it would sell for. Land is not insured, and market value includes it. Carriers run a reconstruction estimator from the square footage, finishes and construction type; ask to see the inputs, because a wrong square footage or a missing basement is the usual reason the limit is short.
Suppose a house would sell for $500,000 and the lot alone is worth $150,000. The dwelling limit should track the $350,000 rebuild plus an extended replacement cushion for the price surge after a regional storm, and it should be adjusted upward when you remodel.
How can I find the right life insurance policy for my family's needs?
Start from your obligations, not a product: what income would need replacing, what debts would need paying, and what future costs, like education, you want covered. Your health, age and budget then determine whether term, whole or indexed universal life fits best.
A licensed advisor can compare quotes across carriers so the policy is sized to your actual numbers. That comparison is what the analysis does.
Do I have to sign up if I am still working?
If you or your spouse are actively employed and covered by that employer's group plan, you can usually delay Part B and Part D without a penalty and enroll later under a special enrollment period when the job or the coverage ends. Whether the employer plan is primary or secondary to Medicare depends on the employer's size, and a small employer's plan can become secondary, which makes delaying Part B costly. Many people take Part A when first eligible because it carries no premium for them, but doing so ends eligibility to contribute to a health savings account, so the timing is worth working out in advance.
Who actually needs an umbrella?
Anyone whose net worth or future earnings would be reached by a judgment above their auto or home limits: a household with equity, retirement savings, a teenage driver, a pool, a dog, a boat, a rental house, or a seat on a nonprofit board. The list is broad because the premium is low relative to the limit.
It is not everyone. A renter with no car, no savings and no dependants has little a judgment could take, and for them the money is better spent raising the liability limits on the policies they do carry. We say so when that is the case.
My landlord requires renters insurance. What are they actually asking for?
Usually two things: a liability limit that meets the lease, and a certificate naming the landlord as an interested party so they are told if the policy cancels. Being an interested party gives the landlord notice, not coverage; your policy still insures you, not them. Some leases ask for the landlord as an additional insured, which extends your liability coverage to claims against them arising from your unit, and most carriers can add it.
The analysis starts with what you already have. Send a declarations page, or answer the questions in the quote flow, and a licensed advisor reads the limits and deductibles against what you own, owe and earn. Gaps get marked, duplicated coverage gets marked, and the same coverages are priced with each carrier we hold an appointment with.
You get a written finding with the numbers side by side: what changes, what it costs, and what it does not buy you. Sometimes the finding is that your current policy is priced fairly and the limits fit; in that case the recommendation is to renew, and we tell you so. There is no fee for the analysis and no obligation to move.
Twenty minutes. Your numbers. No obligation.
If keeping what you have is the right answer, that is the answer we give.